There is a startup myth that refuses to die, mostly because it wears a designer hoodie and speaks in dramatic board-meeting one-liners: if your company is not doubling forever, the unicorn dream is dead. Cute myth. Terrible math.
The truth is far more encouraging, and frankly more useful. Once a company reaches $10 million ARR, the game changes. You are no longer trying to prove you are real. You are trying to prove you can compound. And compounding does not always look like fireworks. Sometimes it looks like 55% growth, strong retention, improving margins, better sales efficiency, and customers who keep buying more while your competitors are still busy making “vision decks” with no renewal base.
That is why “pretty good growth” after $10 million ARR can still build a unicorn. Not overnight. Not with sloppy execution. Not with vibes and a coffee addiction posing as strategy. But with the right retention profile, go-to-market discipline, market size, and valuation timing, absolutely yes.
This is the part founders, operators, and even some investors tend to underestimate: after $10 million ARR, the best companies are not always the ones growing the fastest in a single quarter. They are the ones turning early traction into repeatable, efficient, durable growth. That is where big outcomes are born.
The Big Shift That Happens After $10 Million ARR
Hitting $10 million ARR matters because it changes the conversation around your company. Before that point, every question feels existential. Is the product really working? Is this market big enough? Are customers buying because they love it or because your founder is weirdly persuasive on Zoom?
After $10 million ARR, the business starts to reveal its real shape. By then, a few things usually become visible:
- You can see whether customers actually stay.
- You can tell whether expansion revenue is real or accidental.
- You can measure whether the sales motion is repeatable.
- You can observe whether a category tailwind exists or whether you are dragging the market uphill yourself.
- You can spot whether growth improves as the company scales, or whether it gets more expensive and more chaotic.
That is why $10 million ARR is such an important checkpoint. It is not the finish line. It is where the scoreboard gets turned on.
At $10 Million ARR, Retention Starts Doing Heavy Lifting
In the early years, founders talk nonstop about new logo growth. That makes sense. You cannot expand customers you do not have. But after $10 million ARR, retention and expansion become the quiet engine of company building.
If customers renew at high rates and spend more over time, your business starts compounding in a way that looks almost unfair. Your future growth no longer depends entirely on refilling the bucket. The bucket starts refilling itself.
This is why strong net revenue retention is so powerful. A company with merely good new sales and excellent expansion can outgrow a company with flashy new bookings and weak customer love. The first business is building on concrete. The second is building on a trampoline.
At $10 Million ARR, “Good Enough” GTM Becomes Dangerous
There is also a downside to reaching this stage: whatever is messy in your go-to-market motion becomes painfully expensive. A founder-led sales process that once felt scrappy and heroic starts to feel like hand-carving a ladder while the building is on fire.
After $10 million ARR, sales, marketing, pricing, onboarding, customer success, and expansion cannot behave like distant cousins who only meet at holidays. They have to work as a system. The winners are the companies that build a repeatable engine, not just a charismatic sprint.
Why “Pretty Good Growth” Can Still Create a Unicorn
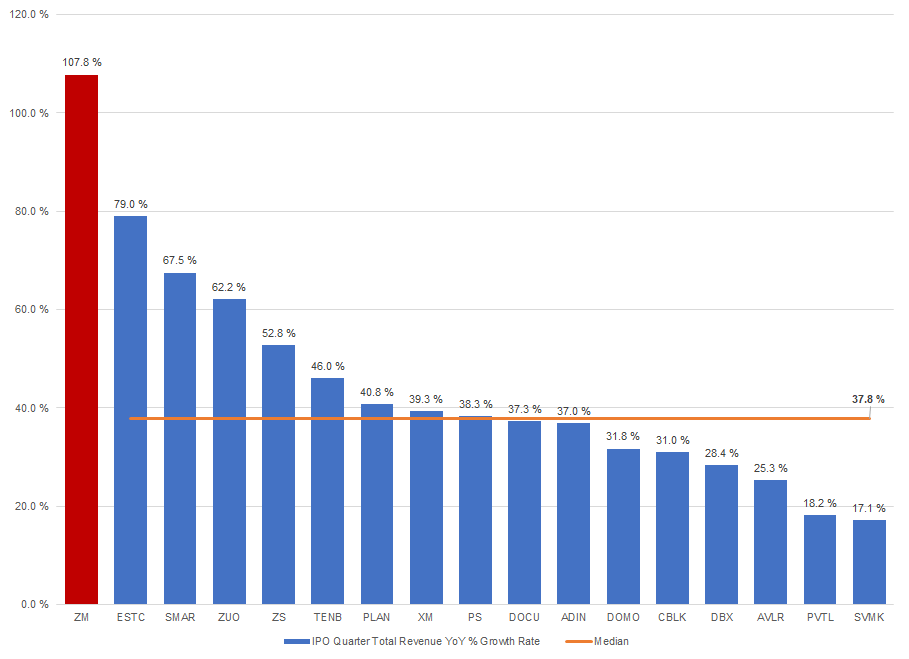
Let’s define the phrase that makes some founders twitch: pretty good growth. In this context, it means growth that is clearly healthy, but not cartoonishly fast. Think something like 40% to 70% annual growth at scale, with strong retention and improving efficiency. No, that does not earn you a cape. Yes, it can still build a monster company.
The reason is simple. Once you are already at $10 million ARR, you do not need impossible growth to become enormous. You need sustained compounding.
Consider an illustrative example:
- Year 1: $10M ARR
- Year 2: $16M ARR at 60% growth
- Year 3: $24M ARR at 50% growth
- Year 4: $34M ARR at roughly 42% growth
- Year 5: $48M ARR at roughly 41% growth
- Year 6: $65M ARR at roughly 35% growth
- Year 7: $85M ARR at roughly 31% growth
That growth curve is not “viral legend” material. Nobody is making a movie trailer about it. But it is exactly the kind of curve that can produce a very valuable company if retention is strong, margins improve, and the market believes growth remains durable. Add a better-than-average expansion model or a strategic category tailwind, and the path to a unicorn becomes very real.
In other words, the critical mistake is assuming a unicorn must be created at $10 million ARR. In many cases, it is built after $10 million ARR through several years of disciplined execution.
Valuation Is a Function of More Than Revenue
A $1 billion valuation is not awarded because a company hit a nice round number and everybody clapped politely. It is awarded because investors believe the company has a credible path to large, durable free cash flow or strategic dominance.
That means valuation is shaped by a bundle of factors:
- Revenue scale
- Growth rate
- Net retention
- Gross margin
- Capital efficiency
- Market size
- Category leadership
- Predictability of expansion
So yes, a company at $10 million ARR growing 50% may not be a unicorn today. But a company at $60 million to $100 million ARR, still growing well, with excellent retention and sane economics, absolutely can be.
The Modern Unicorn Math Is Less Romantic and More Useful
During the frothiest market windows, some startups reached unicorn status earlier than they probably should have. That era created a distorted mental model: raise at a giant valuation as soon as possible, announce the round with a triumphant LinkedIn post, and assume gravity has been repealed.
Gravity, sadly for founders everywhere, remains operational.
Today’s market is more demanding. Investors still pay up for true category leaders, but they are much less likely to ignore efficiency, burn, retention, or margin structure. That is actually good news for strong operators. A company no longer needs to look like a sugar-high spreadsheet to be valuable. It needs to look durable.
This matters because it resets the founder playbook. You do not need to force a unicorn round too early. In many cases, it is smarter to grow into one. Build to $30 million, then $50 million, then $80 million ARR with healthy economics and a category position that gets stronger over time. That is how “pretty good growth” turns into a very large outcome.
Rule of 40 Thinking Helps Explain Why
The Rule of 40 is not magic, but it is useful because it captures a central truth of software: growth and profitability are dance partners, not enemies. Investors increasingly reward businesses that can show both momentum and discipline.
That does not mean every company needs to become wildly profitable early. It means the company should show that growth is not being purchased in a financially reckless way. A business that grows 45% while steadily improving efficiency often tells a much stronger story than a business growing 70% with unraveling margins, rising churn, and a burn rate that could terrify a casino owner.
What Actually Creates Unicorn Potential After $10 Million ARR
1. Retention That Proves the Product Is Deep, Not Just Trendy
Retention is one of the strongest signals that your revenue base will keep compounding. Great companies do not just win customers. They become harder to remove over time. They move from “interesting tool” to “this would break three teams if we canceled it.”
That shift is where valuation power starts to build.
2. Expansion Revenue That Makes the Core Stronger
The best post-$10M ARR companies often land in one team and expand across departments, geographies, or workflows. Sometimes they begin with self-serve adoption and later layer in enterprise sales. Sometimes they start in a narrow wedge and broaden the product suite only after the core is genuinely sticky.
Either way, expansion matters because it increases customer lifetime value without forcing the company to acquire every dollar from scratch.
3. A GTM Motion That Evolves With the Company
A lot of businesses get to $10 million ARR with one playbook and then need a second one to get to $100 million ARR. This is normal. It is not betrayal. It is adulthood.
You might begin with founder sales, then add a small sales team, then build a top-down enterprise motion after product-led adoption reaches critical mass. You might move from a single-channel acquisition model to a multi-channel engine. You might rethink packaging, pricing, or customer success. These are not signs the business is broken. They are signs the business is scaling.
4. Market Size Plus a Strong Wedge
Founders sometimes swing too hard in one of two directions. They either chase a massive market with a vague product, or they build a sharp product in a tiny market and act shocked when the ceiling arrives early.
The sweet spot is a sharp initial wedge inside a market large enough to support years of expansion. That is how a company earns the right to keep compounding after $10 million ARR.
5. Capital Discipline
There is a difference between investing for growth and setting money on fire while calling it ambition. The market has become much better at spotting the difference.
Capital efficiency matters because it gives the company options. A disciplined company can raise from strength, survive a tougher funding market, and avoid getting trapped by a valuation it cannot justify later. That optionality is incredibly valuable, even if it does not fit neatly on a motivational poster.
What Founders Often Get Wrong at This Stage
They Assume Slowing Growth Means the Story Is Over
Growth naturally slows as revenue gets larger. That is arithmetic, not tragedy. Going from $1 million to $2 million ARR is 100% growth. Going from $40 million to $60 million ARR is “only” 50% growth, but it adds twenty times as many dollars. Investors with functioning calculators know this.
They Raise Too High, Too Early
Becoming a unicorn on paper before the business can support it may feel glamorous for about five minutes. After that, it can become a trap. The next round gets harder, recruiting expectations get weird, and every operational wobble feels existential. A healthy business is better than a vanity valuation wearing expensive shoes.
They Expand the Product Too Soon
Many teams try to build a suite before the core product has earned the right to expand. The result is predictable: more roadmap, more confusion, more demos, less actual compounding. A strong core with deep retention usually beats a flimsy bundle of “solutions.”
They Confuse Activity With Repeatability
A company can appear busy and still be fragile. More pipeline, more campaigns, more headcount, more dashboards, more quarterly off-sites with suspiciously expensive snacks. None of that proves the engine works. Repeatability is what matters: can the business produce growth without reinventing itself every quarter?
A Practical Playbook for Building Toward Unicorn Status After $10 Million ARR
- Protect the core. Obsess over retention, onboarding quality, and product value realization.
- Measure expansion deliberately. Know exactly which segments, features, and motions create upsell and cross-sell.
- Sharpen pricing. Underpriced products often hide inside “decent” growth curves. Packaging can unlock meaningful expansion.
- Upgrade GTM in stages. Do not scale a sales motion too early, but do not wait until the company is leaving enterprise demand on the table.
- Track efficiency with honesty. Growth that destroys margin quality is not heroic. It is expensive.
- Choose fundraising timing carefully. Better to raise a strong round that supports the next phase than a headline round that becomes a historical artifact.
- Tell the right story. The best narrative is not “we grew at all costs.” It is “we built a durable compounding machine in a market big enough to matter.”
What the Journey Really Feels Like: Operator Experiences After $10 Million ARR
This stage of company building often feels less like a victory lap and more like switching from driving a fast kart to steering a train that is still being assembled. On paper, things look exciting. Revenue is real. Customers are recognizable. The team is bigger. Investors return your emails faster. But internally, the experience is usually more humbling than glamorous.
One common pattern is that every metric suddenly becomes emotional. At $2 million ARR, a missed quarter can be explained away with a story. At $10 million ARR and beyond, every miss becomes a debate about the model itself. Is win rate slipping? Is CAC creeping up? Are expansions coming from genuine product value or from a few heroic account managers who deserve a statue and a nap?
Another experience founders talk about is the strange grief of outgrowing what used to work. Founder-led selling may have built the first chapter, but now it creates bottlenecks. Early employees who were magical in chaos may struggle in structure. The product that thrilled early adopters may need enterprise controls, security layers, procurement support, and implementation rigor. None of this is as fun as shipping a flashy new feature, but it is often what turns a promising startup into a real company.
There is also a psychological shift around growth itself. Before $10 million ARR, 100% growth feels like the standard everyone is chasing. After $10 million ARR, experienced operators begin to appreciate the beauty of durable 50% growth paired with strong retention and improving efficiency. It is less cinematic, sure. But it is much easier to build a great company out of a business that customers keep renewing than out of one that depends on permanent adrenaline.
Teams at this stage also discover that pricing is not just finance homework. It is strategy. Small changes in packaging, seat expansion, usage tiers, or enterprise add-ons can quietly unlock millions in ARR over time. The companies that learn this early often look “pretty good” for a while, then suddenly look brilliant in hindsight.
And then there is fundraising. Founders often imagine later rounds will feel easier because the company is bigger. In some ways, yes. In other ways, the scrutiny gets sharper. Investors ask tougher questions because now there is enough history to reveal whether the business is compounding or just spending. The good news is that strong operators usually prefer this environment. Flash gets less credit. Discipline gets more.
Perhaps the most underappreciated experience is that category leadership often emerges gradually. It is not always obvious in real time. Sometimes it looks like a steady stream of renewals, slightly larger customers, better references, and a sales cycle that gets less educational each quarter. That is how companies move from “interesting startup” to “default choice.” Once that happens, the road from $10 million ARR to unicorn status stops looking mythical and starts looking operational.
Conclusion
So yes, even with just “pretty good growth,” you can absolutely build a unicorn after $10 million ARR.
But the path is not built on lazy optimism. It is built on compounding. Strong retention. Thoughtful GTM evolution. Better pricing. Capital discipline. A real market. A product that expands. A story investors can believe because customers are already proving it true.
The founders who win this stage are usually not the ones trying hardest to look legendary. They are the ones building a company that gets a little stronger, a little more efficient, and a little harder to compete with every quarter.
That may not sound sexy. It does, however, sound suspiciously like how giant software companies are actually made.