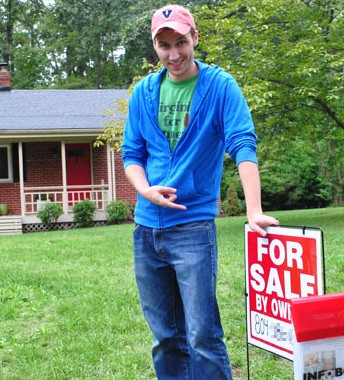
Selling your first house feels a little like finishing a group project with a bank, a title company, a real estate agent, an inspector, a buyer, three mysterious fees, and at least one printer that runs out of ink at the worst possible moment. You see the sale price and think, “Great! We made money!” Then the closing statement arrives and quietly says, “Not so fast, spreadsheet enthusiast.”
So, did we make a profit selling our first house? The honest answer is: maybe. A home sale profit is not simply the difference between what you paid and what the buyer paid. The real answer comes after subtracting the mortgage payoff, seller closing costs, agent commissions, repairs, concessions, taxes, and the improvements you made along the way. In other words, the house may have sold for more than you bought it for, but that does not automatically mean your wallet left the party wearing a crown.
This guide breaks down how to calculate profit from selling a house, what costs quietly nibble at your proceeds, how taxes work, and what first-time sellers often forget. We will keep it practical, a little funny, and grounded in real U.S. housing and tax principles.
What “Profit” Really Means When Selling A House
In everyday conversation, people usually define home profit like this:
Sale price minus purchase price equals profit.
That is a decent cocktail-party answer, but it is not the full financial picture. The better formula is:
Net sale proceeds minus adjusted cost basis equals real profit.
Your net sale proceeds are what is left after selling costs and mortgage payoff. Your adjusted cost basis is usually your original purchase price plus eligible capital improvements and certain buying costs. The result is your real gainor, in less glamorous cases, your real loss.
The Basic Home Sale Profit Formula
Here is a simple way to estimate whether you made money selling your first home:
Step 1: Start With The Final Sale Price
This is the contract price the buyer agreed to pay. For example, let’s say your first house sold for $420,000.
Step 2: Subtract Your Mortgage Payoff
If you still owed $285,000 on the mortgage, that balance gets paid off at closing. You do not keep that money; your lender does. The lender is not emotionally attached to your kitchen backsplash, but it is very attached to being repaid.
Step 3: Subtract Seller Closing Costs
Seller costs may include title fees, escrow fees, transfer taxes, recording fees, attorney fees in some states, prorated property taxes, HOA transfer charges, and other local expenses. Many sellers also pay real estate commissions or negotiated buyer-agent compensation, depending on the listing agreement and market conditions.
Step 4: Subtract Repairs, Credits, And Concessions
If you gave the buyer a $5,000 closing cost credit, repaired the roof, replaced appliances, or agreed to pay for a home warranty, those costs reduce your walk-away money.
Step 5: Compare What Is Left To Your Total Investment
Now compare your final proceeds to what you invested in the home, including your original down payment, closing costs when you bought, and major improvements. That gives you a clearer answer than simply cheering at the sale price.
A Realistic Example: Did We Actually Make Money?
Let’s run the numbers with a realistic example.
Suppose you bought your first home for $320,000. You put money into the property over several years: a new HVAC system, updated flooring, a modest kitchen refresh, landscaping, and enough paint samples to qualify as modern art. Your eligible improvements totaled $28,000. Your adjusted basis is now roughly $348,000, not counting every possible tax detail.
You sell the home for $420,000. At first glance, it looks like a $100,000 gain. Cue the confetti cannon.
But then come the deductions:
- Mortgage payoff: $285,000
- Agent commissions and negotiated compensation: $22,000
- Seller closing costs: $8,000
- Buyer repair credit: $4,000
- Pre-sale repairs and staging: $6,000
- Moving costs: $3,500
Your closing check might be around $95,000 after the mortgage payoff and transaction costs. That feels fantasticand it is! But your taxable or economic profit is not automatically $95,000. You must compare the sale price, minus selling expenses, against your adjusted basis.
If your selling expenses total $34,000, your amount realized is approximately $386,000. Subtract your adjusted basis of $348,000, and your estimated gain is $38,000. So yes, in this example, you made a profitbut not the giant cartoon money bag you may have imagined when the offer arrived.
Why The Sale Price Can Be Misleading
The sale price is the number everyone remembers. It is also the number that makes relatives say, “Wow, you must be rich now!” Unfortunately, the sale price is only the headline. The closing statement is the fine print.
A home can sell for $80,000 more than you paid and still produce a much smaller real gain after commissions, taxes, repairs, concessions, mortgage interest paid over the years, and maintenance. That does not mean selling was a bad decision. It simply means real estate profit is not the same as winning a game show.
Common Costs That Reduce Home Sale Profit
1. Real Estate Agent Commissions
Commissions are negotiable, but they remain one of the largest seller expenses. Depending on the agreement, local market, and compensation structure, sellers may pay a listing-agent commission and may also offer or negotiate buyer-side compensation. Since industry rules and practices have changed in recent years, sellers should read listing agreements carefully instead of relying on “that’s how it has always worked.”
2. Seller Closing Costs
Closing costs vary widely by state, county, price point, and contract terms. Seller costs can include title services, transfer taxes, settlement fees, recording fees, attorney fees, HOA charges, payoff fees, and prorated property taxes. These are usually deducted from proceeds at closing, so you may not write a separate checkbut you still pay them.
3. Repairs Before Listing
Before selling, many homeowners spend money fixing obvious issues: peeling paint, broken fixtures, tired landscaping, squeaky doors, stained carpet, or that one cabinet handle that has been “on the weekend list” since 2019. Some repairs help the home sell faster or for more money. Others are just the cost of convincing buyers that the house is not held together by optimism.
4. Buyer Concessions
In a softer market, sellers may offer concessions such as closing cost assistance, repair credits, mortgage-rate buydown help, or home warranties. These concessions can keep a deal alive, but they reduce your net proceeds. A $7,500 credit does not feel dramatic during negotiation, but it looks very real on the settlement statement.
5. Mortgage Payoff And Liens
Your outstanding mortgage, second mortgage, HELOC, or other liens must be paid off at closing. If you borrowed against the house, that debt comes out before your proceeds hit your bank account.
6. Moving And Transition Costs
Moving costs are not always listed on the closing statement, but they are part of the real-life financial result. Movers, storage, deposits, temporary housing, utility transfers, cleaning, and pizza for the friends you bribed with “just a few boxes” all count.
What About Taxes On The Profit?
The good news is that many U.S. homeowners who sell a primary residence qualify for a capital gains exclusion. Generally, if the home was your main home and you meet ownership and use tests, single filers may be able to exclude up to $250,000 of gain, while married couples filing jointly may be able to exclude up to $500,000.
That does not mean every sale is tax-free. You may owe taxes if your gain exceeds the exclusion, if the property was not your primary residence, if you used it as a rental, if you claimed depreciation, or if you do not meet the timing rules. Tax rules can be surprisingly picky, like a toddler choosing a breakfast spoon, so keep documents and ask a qualified tax professional when the numbers matter.
Adjusted Basis: The Secret Ingredient In The Calculation
Your adjusted basis is the tax-world version of “what you really have invested in the home.” It often starts with the purchase price, then increases for eligible capital improvements. Improvements are different from ordinary repairs. A new roof, new HVAC system, major remodel, room addition, or permanent upgrade may increase basis. Replacing one cracked tile usually does not.
Examples of possible basis-increasing improvements include:
- Adding a deck, room, garage, or bathroom
- Installing a new roof or HVAC system
- Upgrading plumbing or electrical systems
- Major kitchen or bathroom renovations
- Permanent landscaping improvements
Keeping receipts is not glamorous. Nobody frames a water-heater invoice. But those records can matter when you calculate gain. A messy folder labeled “house stuff” is better than nothing, though a digital folder is less likely to be eaten by time, dust, or a suspiciously damp basement.
Did Homeownership Itself Make Us Wealthier?
Even if the calculated profit is modest, homeownership may still have improved your financial position. Every principal payment reduced your loan balance. Appreciation may have increased your equity. Forced savingsalso known as “the mortgage company insists you pay every month”can build wealth over time.
However, it is important to be honest. Homeownership also comes with costs renters do not always face directly: maintenance, insurance, property taxes, interest, repairs, HOA dues, and the occasional appliance that chooses a holiday weekend to dramatically retire.
A true profit analysis should consider both the sale result and the cost of owning the home. Still, for many first-time sellers, the big win is equity: the difference between the home’s value and the mortgage balance. Equity can become the down payment for the next home, a debt payoff tool, an emergency cushion, or the first calm breath after years of budgeting.
Signs You Probably Made A Profit
You likely made a profit selling your first house if:
- Your sale price was meaningfully higher than your purchase price.
- You owned the home long enough for appreciation to outpace selling costs.
- You did not over-improve for the neighborhood.
- Your mortgage payoff was much lower than the sale price.
- You kept concessions, repairs, and closing costs under control.
- Your gain was within the primary residence exclusion limits.
Signs The Profit Was Smaller Than Expected
Your profit may be smaller than expected if you sold shortly after buying, paid high transaction costs twice, made expensive upgrades that did not increase value, gave large buyer concessions, or bought during a market peak and sold during a slower market.
Short ownership periods are especially tricky. Buying and selling real estate is expensive. If you sell too soon, appreciation may not have enough time to outrun closing costs, commissions, repairs, and moving expenses. That is why many homeowners who sell after only one or two years are surprised by how little they keep.
How To Calculate Your Own First-House Profit
Use this simple worksheet-style approach:
- Write down your final sale price.
- Subtract agent commissions and seller-paid compensation.
- Subtract seller closing costs and transfer taxes.
- Subtract buyer credits, concessions, and repair allowances.
- Subtract pre-listing repairs, staging, cleaning, and moving costs for your personal analysis.
- Subtract your mortgage payoff to estimate cash received.
- Calculate your adjusted basis: purchase price plus eligible improvements and certain purchase costs.
- Compare your amount realized with your adjusted basis to estimate gain.
- Review whether the home-sale tax exclusion applies.
This gives you two useful answers: how much cash you walked away with and whether you had a true gain after accounting for your investment.
Our Experience Selling A First House: The Emotional Math
Now let’s talk about the experience side, because selling a first home is not just math. It is math wearing muddy shoes and carrying memories in a cardboard box.
When we first asked, “Did we make a profit selling our first house?” we were focused on the sale price. That number looked exciting. It was higher than our purchase price, which made us feel like tiny real estate geniuses. We briefly considered wearing sunglasses indoors. Then the estimated net sheet arrived, and reality cleared its throat.
The first surprise was how many line items appeared before the final number. Commission, title fees, escrow fees, payoff amount, taxes, credits, and recording charges all marched across the page like they had been waiting years for their big moment. None of them cared that we had spent weekends improving the house instead of relaxing like normal people.
The second surprise was the cost of getting the house ready. We knew we would paint and clean. We did not know we would suddenly become deeply concerned about mulch, baseboards, grout lines, lightbulbs, cabinet hardware, and whether the front porch looked “welcoming” or “mildly tired.” Selling a house turns ordinary people into amateur hotel inspectors.
We also learned that not every improvement returns dollar for dollar. Some upgrades helped the home show better, but they were not magical profit machines. Fresh paint? Great. Clean landscaping? Worth it. Spending a fortune on a hyper-specific design choice two weeks before listing? Probably not. Buyers love a nice house, but they rarely want to reimburse you for your emotional relationship with designer tile.
The negotiation stage taught us another lesson: the offer price is not always the final story. Inspection items can lead to repair requests or credits. Appraisal concerns can create pressure. A buyer may ask for closing cost help. Each concession can be reasonable, but each one also trims your proceeds. It is death by a thousand polite addendums.
Still, the process was not negative. We did walk away with money. More importantly, we walked away with options. The equity from the first house gave us flexibility for the next chapter. It helped us understand how powerful principal payments and appreciation can be over time. It also taught us that financial wins do not always look as dramatic as social media suggests.
One of the best things we did was review the closing statement line by line. It was not thrilling. No one is making popcorn for “Settlement Statement Night.” But it helped us understand where the money went and prevented us from confusing gross sale price with real profit. We saved the final statement, repair receipts, improvement records, and purchase documents for tax time.
If we could go back, we would track home improvements better from day one. Not just the big projects, but the dates, costs, invoices, and whether each item was a repair or an improvement. We would also ask for a seller net sheet earlier, before listing, so we could estimate different sale-price scenarios. Knowing the numbers ahead of time makes negotiation feel less like a haunted house.
Our biggest lesson was simple: profit is not only about selling high. It is about buying wisely, maintaining the home, improving strategically, controlling transaction costs, and understanding the tax rules. A first home can be a stepping stone, a savings vehicle, a life classroom, and occasionally a very expensive reminder that water heaters have no loyalty.
So, did we make a profit selling our first house? Yesbut the real profit was smaller, smarter, and more complicated than the sale price suggested. And honestly, that is the most first-house lesson imaginable.
Conclusion: So, Did We Make A Profit?
The answer depends on which number you are looking at. If your sale price was higher than your purchase price, you may feel profitable. If your net proceeds exceeded your total investment after selling expenses, improvements, mortgage payoff, and concessions, you probably did make a real profit. If your gain qualified for the primary residence exclusion, you may have kept more of that profit from being taxed.
The smartest way to answer the question is to calculate it carefully. Start with the sale price, subtract selling costs, subtract the mortgage payoff, review your adjusted basis, and check the tax rules. Do not rely on vibes, neighbor opinions, or the emotional high of seeing a big number on the purchase agreement.
Selling your first house can be exciting, stressful, profitable, confusing, and strangely nostalgic all at once. You are not just selling walls and a roof. You are closing a chapter. If the math works out, wonderful. If the profit is smaller than expected, you still gained experience, equity knowledge, and probably a very strong opinion about caulk.
SEO Tags
Note: This article is for educational and editorial purposes only. Home sale profit, tax treatment, and closing costs vary by state, contract, lender, and personal situation, so sellers should review final documents and consult qualified real estate and tax professionals before making financial decisions.