Independent insurance agents do not usually become industry heroes by wearing capes. More often, they do it by answering client calls, explaining confusing policy language, hiring the right people, mentoring young professionals, and showing up when lawmakers need to hear how insurance decisions affect real businesses and families. That may not sound cinematic, but in the independent agency world, it is practically an action moviewith fewer explosions and more renewal meetings.
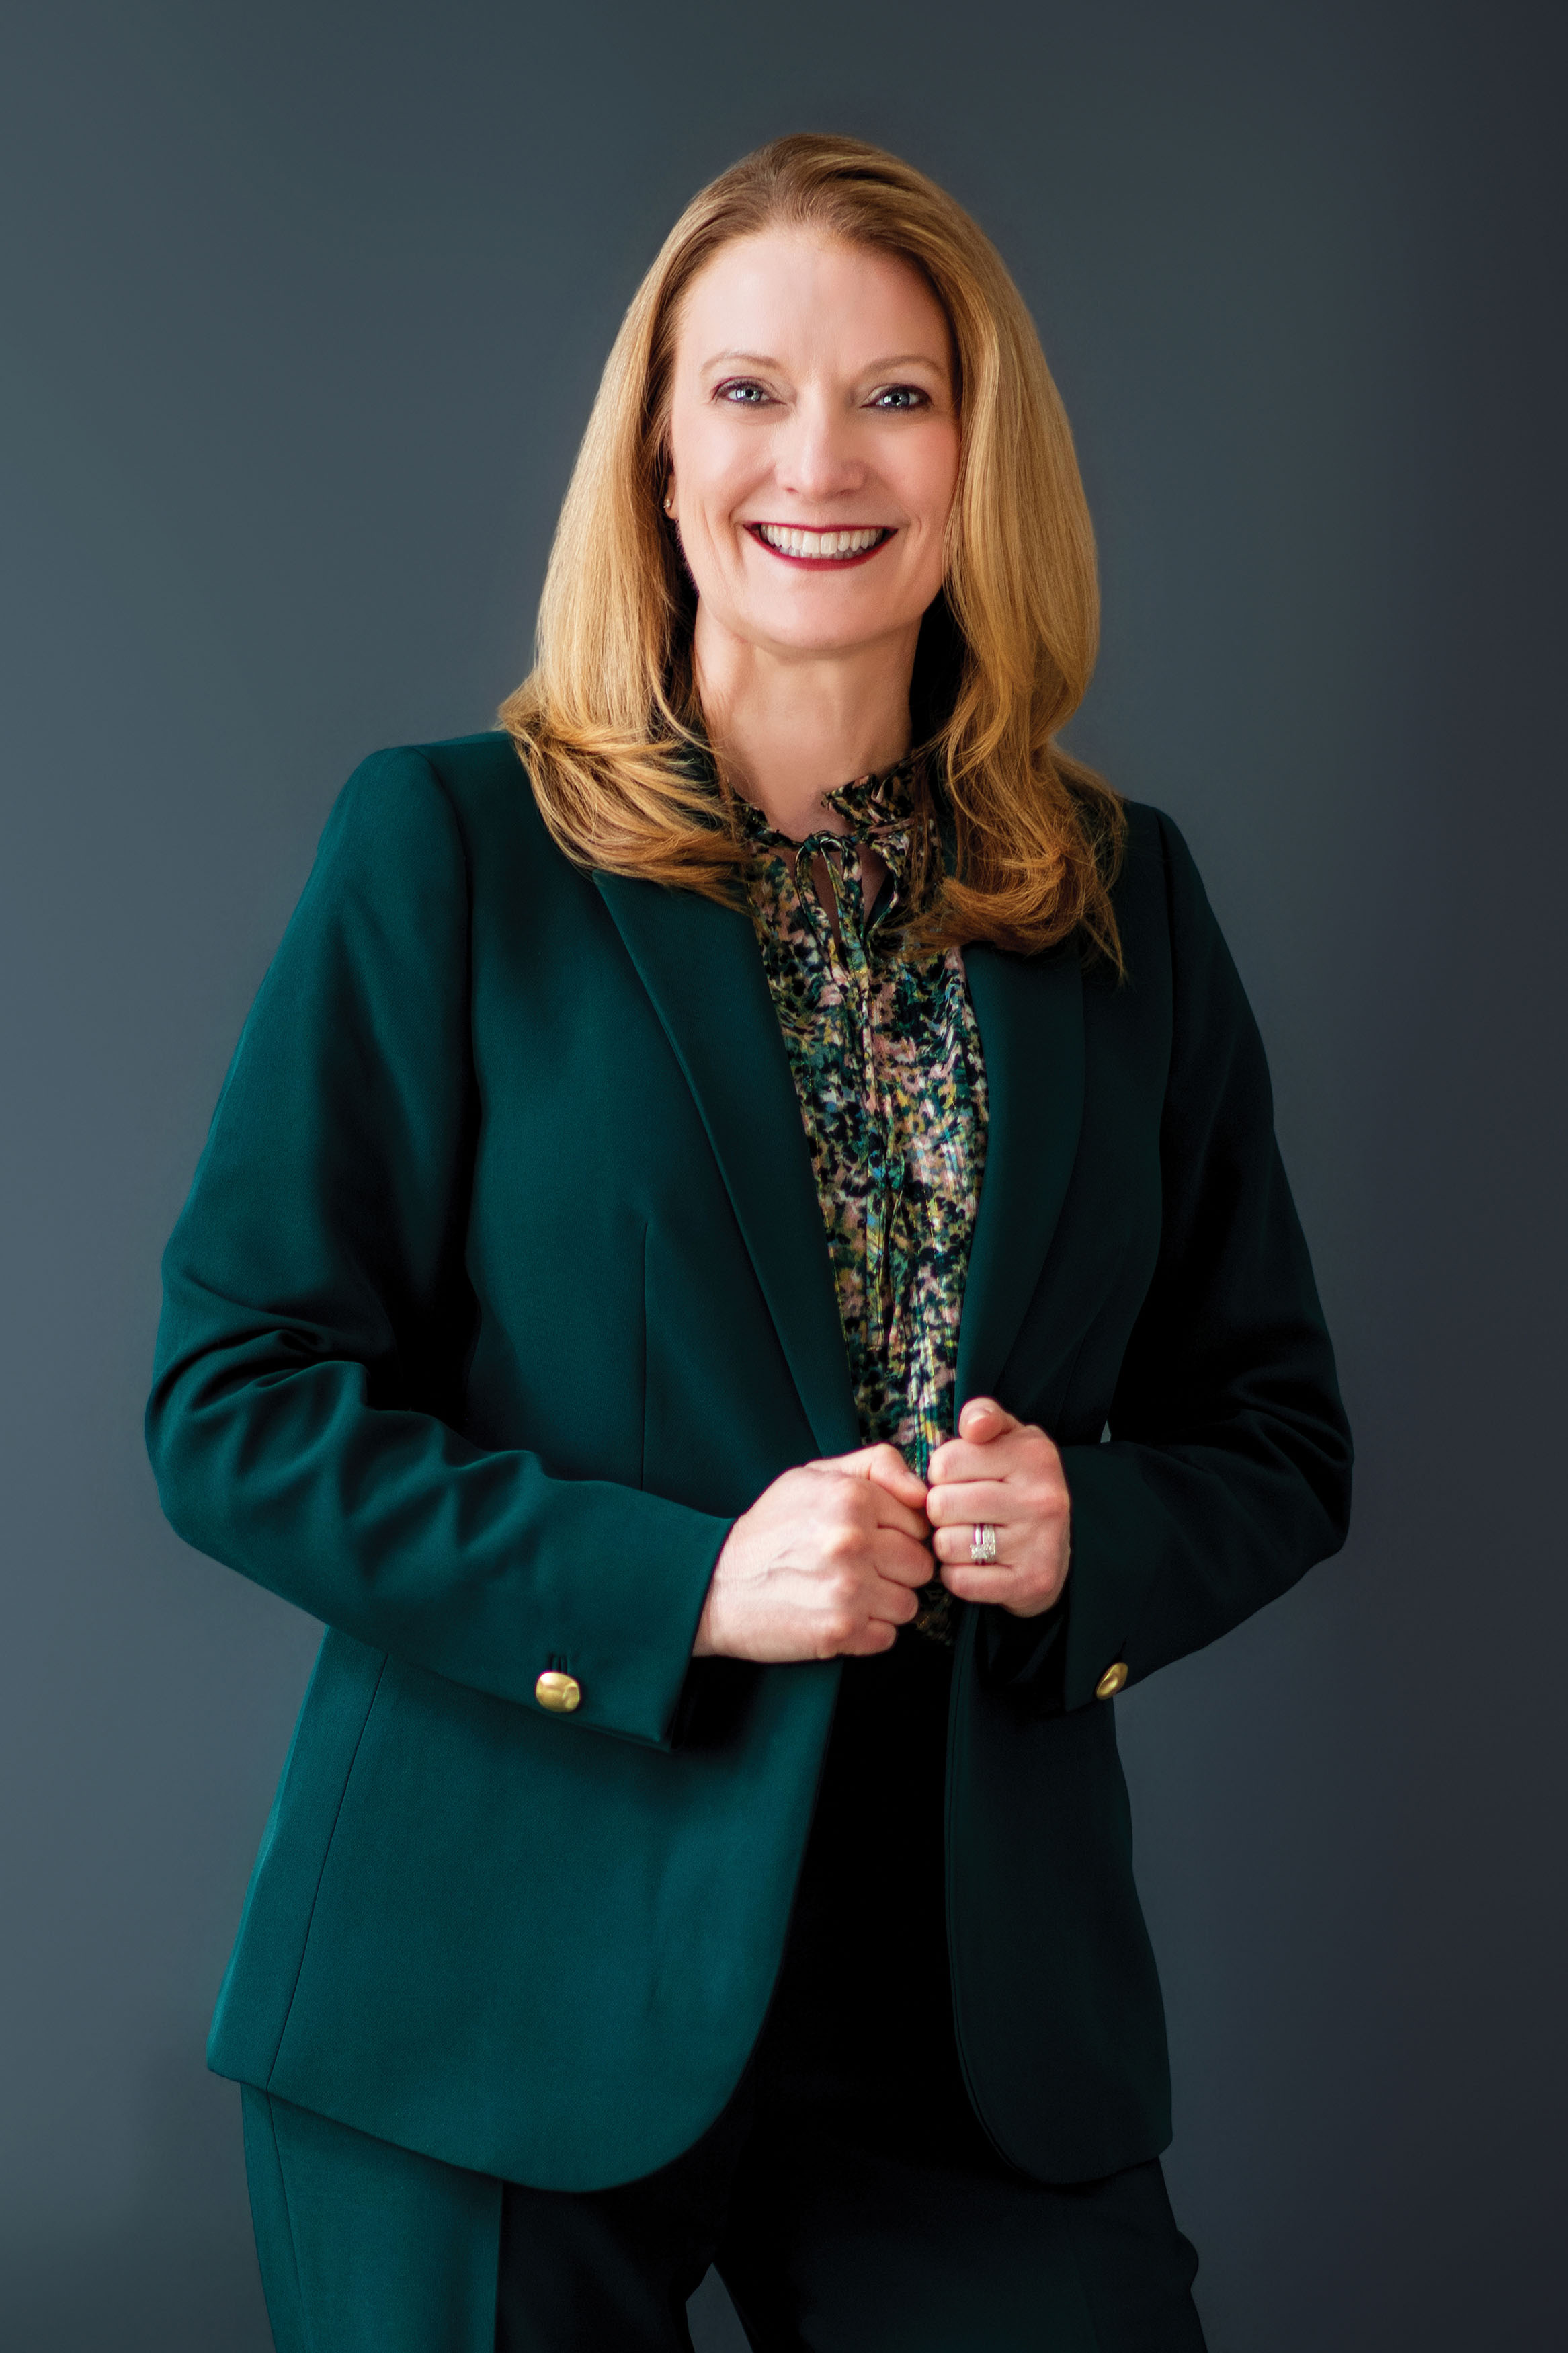
The IA Magazine feature “Declaration of Independents: Michelle O’Connor” highlights Michelle O’Connor, president of O’Connor Insurance Associates in Charlotte, North Carolina. Her story is not simply a profile of a successful agency leader. It is a snapshot of what modern independent insurance leadership looks like: local service, industry advocacy, thoughtful technology adoption, and the very real small-business discipline required to keep an agency growing for decades.
For readers searching for Michelle O’Connor IA Magazine, Declaration of Independents, O’Connor Insurance Associates, independent insurance agents, or Big I advocacy, this article takes the original profile as a starting point and expands the bigger message behind it. Spoiler alert: independence is not the easy road. It is the road where you get to choose your carriers, your culture, your tools, your clients, and occasionally, your brand of office coffee. That last one matters more than people admit.
Who Is Michelle O’Connor?
Michelle O’Connor is a leading independent insurance professional connected with O’Connor Insurance Associates, a family-owned agency based in Charlotte. Her professional background includes more than two decades in insurance, business leadership, agency operations, and client service. The agency’s public profile describes her as a co-president and treasurer who has helped guide growth, retention, operations, and innovation while keeping a client-first culture at the center of the business.
What makes her IA Magazine profile compelling is not just the title on the business card. It is the path. O’Connor and her husband built their agency with a clear understanding that membership in the Independent Insurance Agents of North Carolina, often known as IIANC, would be important from the beginning. That decision says a lot. Some new business owners treat association involvement like a “nice-to-have” bonus, similar to the office plant nobody remembers to water. O’Connor’s approach was different: she recognized early that professional community, advocacy, and shared knowledge could become part of the agency’s foundation.
Why the “Declaration of Independents” Theme Works
The title Declaration of Independents is clever because it does more than make a patriotic pun. It captures the identity of the independent agency channel. Independent agents are not tied to a single insurance company. They work with multiple carriers, compare coverage options, and advise clients based on a broader view of the market. That flexibility is the core promise of the independent model.
In practice, independence means responsibility. A captive agent may have one company’s products to explain. An independent agency must manage carrier relationships, underwriting appetites, technology platforms, compliance needs, client expectations, claims conversations, and local market realities. It is like running a restaurant where every table ordered from a different menu, and the kitchen is also asking you to update your cybersecurity policy.
That is why O’Connor’s story fits the series. Her career shows that independence is not isolation. The best independent agents build networks: state associations, national associations, peer groups, technology partners, carrier relationships, university programs, and community ties. In other words, independent does not mean “alone in the wilderness with a rating worksheet.” It means free to serve clients while still smart enough to collaborate.
Advocacy as a Business Skill, Not a Side Quest
One of the strongest themes in the IA Magazine profile is legislative advocacy. O’Connor describes her interest in advocacy as rooted in the uniqueness of North Carolina’s insurance system and the realization that meaningful change often happens at the legislative level. That point deserves attention because many agency owners think advocacy is something “other people” dousually people with suits, microphones, and unusually strong opinions about committee schedules.
But for independent insurance agents, advocacy is practical. Laws and regulations affect premium affordability, coverage availability, claims costs, flood insurance, licensing, carrier operations, and consumer protection. When agents participate in political action committees, state associations, and national legislative conversations, they help translate real-world insurance problems into language policymakers can understand.
That matters because insurance is often misunderstood by the general public. Consumers may see only the bill, the deductible, or the confusing declarations page. Agents see the full chain: risk, underwriting, claims, litigation trends, regulation, reinsurance pressure, carrier appetite, and customer frustration. Advocacy gives agents a way to say, “Here is what is actually happening on Main Street,” before policy decisions are made in rooms where nobody has had to explain an auto renewal increase to a small-business owner at 4:45 p.m. on a Friday.
Legal System Abuse and the Premium Conversation
In the IA Magazine discussion, O’Connor points to legal system abuse as one of the top issues for agents to discuss. This topic has become increasingly important across the property and casualty insurance industry. Legal system abuse generally refers to litigation-related practices that increase the cost and time needed to settle claims. It can include inflated claims, aggressive litigation strategies, third-party litigation funding, and other factors that push claim severity higher.
Why should clients care? Because claims costs do not live in a secret basement separate from premiums. When claim costs rise, insurers adjust pricing, underwriting rules, deductibles, and available coverage. The result can be higher premiums, tighter options, and more difficult conversations between agents and policyholders. Nobody enjoys those conversations. They are the insurance equivalent of telling someone their favorite diner now charges extra for fries.
This is where the independent agent’s role becomes especially valuable. Agents can explain not only what changed on a policy, but why broader market forces may be affecting rates. A strong agent does not simply say, “Your premium went up.” A strong agent explains market conditions, reviews options, checks coverage gaps, and helps the client make a responsible decision instead of panic-clicking the cheapest quote on the internet.
Technology: Useful Tool or Expensive Desk Ornament?
Another memorable point from O’Connor’s IA Magazine profile is her view of technology. Her message is refreshingly practical: do not adopt technology simply because it is shiny; adopt it because it works for the agency and helps agents continue doing what they do bestserving clients.
That advice should be printed on a coffee mug and handed out at every insurance technology conference. The independent agency channel is surrounded by software promises: automation, artificial intelligence, data analytics, digital engagement, comparative rating, client portals, text messaging, chatbots, and dashboards that appear to contain twelve dashboards inside them. Some tools truly save time and improve service. Others create new work with the enthusiasm of a raccoon in a file cabinet.
O’Connor’s perspective is grounded in operational reality. Technology should support the relationship, not replace it. If automation helps an agency follow up faster, reduce duplicate entry, identify coverage gaps, or improve renewal workflows, it has value. If it creates confusion, weakens communication, or forces the team into awkward processes that do not match the agency’s service model, it may be a very expensive screensaver.
101 Weston Labs and the Agent Voice in InsurTech
The profile also references 101 Weston Labs, an InsurTech accelerator connected with IIANC and focused on solutions for the independent agency channel. Its purpose is important: bring technology developers closer to the agents who will actually use the products. That may sound obvious, but the business world has a long and glorious history of building tools for users without asking users what they need. The result is often software that technically functions but emotionally feels like assembling furniture without instructions.
For independent agents, involvement in InsurTech development is not just trendy. It is strategic. Agencies need tools that reflect their workflows: multi-carrier quoting, policy servicing, claims advocacy, account rounding, documentation, compliance, renewals, and relationship management. When startups get feedback from working agents, they can build products that solve real problems instead of imaginary pain points invented in a conference room with excellent snacks.
O’Connor’s comments about technology and 101 Weston Labs point to a broader leadership principle: innovation should be shaped by practitioners. Agents should not wait for the future to arrive in a box with a subscription fee. They should help design it.
Independent Agencies Are Small Businesses First
One of O’Connor’s most useful pieces of advice for new agency owners is that they are not just selling insurance; they are running a small business. That distinction is huge. Selling insurance is the product activity. Running an agency includes marketing, accounting, hiring, training, compliance, management systems, customer experience, vendor contracts, cybersecurity, producer compensation, payroll, and the emotional gymnastics of leadership.
New agency owners sometimes underestimate that complexity. They may enter the business because they are strong producers, excellent relationship builders, or experienced account managers. Those skills matter, but ownership adds a second job: building the machine that allows the agency to operate consistently. A great producer can win accounts. A great owner builds systems so the agency can serve clients well even on the days when three people are out, the carrier portal is down, and the printer has chosen violence.
O’Connor’s story illustrates that sustainable agency growth requires more than hustle. It requires structure, culture, association involvement, technology discipline, and a willingness to keep learning. In a hard market, that discipline becomes even more important because clients need guidance, teams need support, and owners need enough operational clarity to avoid making every decision in emergency mode.
The Human Side of Independent Insurance
Insurance may be built on contracts, but agencies are built on trust. O’Connor’s public agency biography emphasizes personalized service, family ownership, client care, and community focus. That combination is not old-fashioned. In fact, it may be more relevant than ever.
Consumers can get quotes online in minutes. They can compare rates, watch explainer videos, and receive automated emails that start with “Great news!” even when the news is aggressively average. But when coverage gets complicated, when a claim occurs, or when a business owner needs to understand risk beyond price, human guidance matters.
Independent agents often become translators. They translate insurance language into everyday decisions. They explain why replacement cost matters, why a business owners policy may not cover every exposure, why cyber liability is not just for giant companies, why flood insurance deserves attention outside coastal postcards, and why “full coverage” is not a magic spell.
Lessons for Agency Owners from Michelle O’Connor’s Profile
1. Join the professional conversation early
O’Connor’s early commitment to IIANC shows the value of getting involved before a crisis. Associations provide education, advocacy, peer learning, market insight, and leadership pathways. The agency owner who waits until the storm arrives may still get help, but the one who already has relationships will be better prepared.
2. Treat advocacy as client service
Advocacy is not separate from serving clients. When agents support smart insurance policy, explain market pressures, and engage with lawmakers, they are defending the conditions that allow consumers and businesses to access reliable coverage.
3. Use technology with a purpose
Every agency needs technology, but not every tool deserves a seat at the table. The best technology reduces friction, improves communication, and gives staff more time for high-value client work.
4. Remember that ownership is bigger than sales
An agency is a business. That means leadership, finance, culture, operations, and strategy must receive as much attention as production. Otherwise, growth can become chaos wearing a nice logo.
5. Keep developing the next generation
O’Connor’s involvement with education and emerging professionals highlights a critical industry need. Independent agencies must attract young talent, mentor future leaders, and show students that insurance is not boring. It is risk, finance, law, psychology, technology, disaster recovery, entrepreneurship, and customer service all rolled into one surprisingly durable career path.
Why This IA Magazine Feature Matters
The value of Declaration of Independents: Michelle O’Connor is that it takes a big industry conversation and makes it personal. Advocacy is not abstract when it comes from someone who runs an agency. Technology is not theoretical when it affects daily workflows. Leadership is not a buzzword when it involves employees, clients, carriers, and community responsibilities.
IA Magazine’s profile works because O’Connor represents a familiar but underappreciated type of industry leader: the independent agency professional who builds locally while thinking nationally. Her work reflects the balance many successful agencies must strike. They need to remain personal without becoming outdated, efficient without becoming robotic, profitable without becoming transactional, and independent without becoming disconnected.
That balance is not easy. But it is the future of the independent agency system. Agencies that can advocate, adapt, educate, and preserve trust will remain relevant even as insurance shopping becomes more digital and market conditions become more complex.
Experience-Based Reflections: What Agency Leaders Can Take Away
Anyone who has worked with independent agencies, supported small businesses, or watched a family-owned company grow knows that the public success story usually hides years of unglamorous work. The polished website, the leadership title, the magazine feature, and the community reputation are only the visible part. Underneath are countless decisions about staffing, service standards, carrier relationships, workflows, client communication, and how to keep going when the market gets difficult.
The topic Declaration of Independents: Michelle O’Connor – IA Magazine brings to mind a common experience in the independent agency world: the owner who starts the day as a strategist, becomes a claims counselor by lunch, turns into a technology troubleshooter in the afternoon, and ends the day reviewing financial reports. That variety can be exhausting, but it is also why independent agency work attracts entrepreneurial people. No two days are identical. Some days bring new business wins. Other days bring billing questions, underwriting surprises, and a client who says, “I just bought a building yesterdayam I covered?” Deep breath. Here comes the fun.
One practical experience related to this topic is the importance of explaining insurance in plain English. Many clients are intelligent but busy. They do not want a lecture on policy architecture; they want to know what is covered, what is not covered, what could hurt them financially, and what choices they have. The best independent agents do not show off complexity. They simplify it. They make clients feel informed rather than embarrassed. That skill is part technical knowledge and part emotional intelligence.
Another experience is the challenge of choosing technology. Agencies often feel pressure to modernize quickly. A vendor demo can make every platform look like the answer to civilization’s problems. But real agency life is messier. Staff adoption matters. Data quality matters. Carrier integration matters. Client preferences matter. A tool that saves five minutes for one person but creates twenty minutes of cleanup for another is not innovation; it is digital clutter wearing a blazer. O’Connor’s practical stance on technology reflects what many agencies learn the hard way: buy tools for actual workflows, not imaginary perfection.
Advocacy also becomes more meaningful with experience. At first, legislative issues may seem distant from daily agency operations. Then a market tightens, premiums rise, coverage becomes harder to place, or a regulation changes how agents communicate with clients. Suddenly, advocacy is not abstract. It is connected to every renewal conversation and every client who asks, “Why is this happening?” Agency leaders who participate in associations are better equipped to answer that question with context instead of helpless shrugging.
There is also a people lesson. Independent agencies compete not only for clients but for talent. Young professionals want mentorship, growth, purpose, and modern tools. They also want to know that insurance is more than paperwork. Leaders like O’Connor help tell that story. Insurance careers involve problem-solving, community protection, financial resilience, and relationship building. When a claim happens, the work becomes very real very fast. That is when a good agent stops being a line item and becomes the person the client is relieved to know.
Finally, the experience behind this topic shows that independence is a discipline. It requires owners to make choices every day: which markets to pursue, which clients to serve, which tools to adopt, which people to hire, which industry issues to support, and which values to protect. Michelle O’Connor’s IA Magazine profile is valuable because it reminds agency owners that independence is not just a distribution model. It is a leadership mindset. It says, “We will build something local, useful, resilient, and connected.” That may not fit on a bumper sticker, but it is a pretty good declaration.
Conclusion
Declaration of Independents: Michelle O’Connor – IA Magazine is more than a profile of one respected insurance leader. It is a useful case study in how independent agencies can thrive in a changing market. Michelle O’Connor’s story highlights the importance of association involvement, legislative advocacy, smart technology adoption, small-business discipline, and client-centered service.
For independent agents, the message is clear: do not wait for change to happen around you. Join the conversation, understand the issues, choose technology carefully, mentor future professionals, and remember that the agency’s greatest advantage is not just access to multiple carriers. It is trust. In insurance, trust is not a soft skill. It is the whole business.